PublicSphere Live
Features
NRS Reform: Building a More Efficient Revenue System for Nigeria’s Economic Transformation
The transition from the Federal Inland Revenue Service (FIRS) to the Nigeria Revenue Service represents an important institutional development in this direction
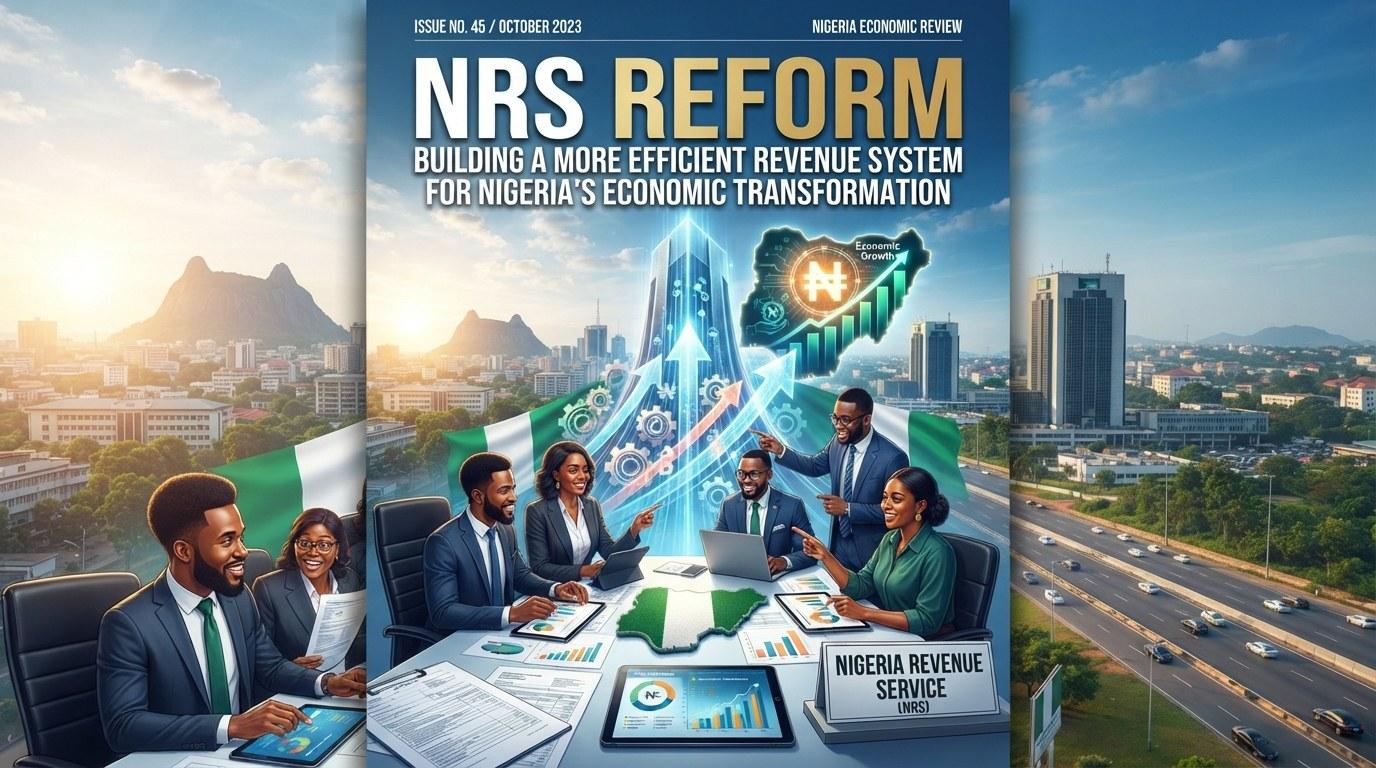
The positive story of the Nigeria Revenue Service (NRS) reform lies in its potential to move the country away from a revenue system defined largely by the collection of taxes towards a more efficient, transparent, technology-driven institution capable of supporting businesses, widening compliance and strengthening the financial foundation of national development.
For Nigeria, where public expectations continue to rise against the background of competing demands for infrastructure, healthcare, education, security and social protection, the effectiveness of the tax administration system is central to the country's economic future. A more capable revenue service can help the government finance essential services, reduce excessive dependence on borrowing and oil receipts, and create a more predictable environment in which businesses can plan, invest and expand.
The transition from the Federal Inland Revenue Service (FIRS) to the Nigeria Revenue Service represents an important institutional development in this direction. More than a change of name, the reform presents an opportunity to modernise revenue administration, improve coordination, strengthen accountability and build a tax system better suited to the realities of a changing economy.
Its ultimate significance, however, will be measured not simply by the amount of revenue collected, but also by how effectively the new institution serves taxpayers, supports productive enterprise and helps establish a fairer relationship between the government and the citizens whose contributions sustain public expenditure.
Revenue Growth Signals a Changing Economy
The most visible evidence of the reform's impact is the significant increase in tax collections recorded over the past three years, providing an indication of how stronger administration, improved compliance and the deployment of technology can expand the resources available to government without relying exclusively on the oil sector.
According to figures reported by The Punch from the Presidency's Economic Snapshot Report, tax collections increased from ₦12.3 trillion in 2023 to ₦21 trillion in 2024 and ₦28.3 trillion in 2025, while the NRS generated ₦21.6 trillion in the first half of 2026, representing a 49 per cent increase over the ₦14.27 trillion recorded in the corresponding period of 2025.
The figures demonstrate the growing capacity of Nigeria's revenue administration to mobilise domestic resources at a time when the country needs sustainable funding for development. They also suggest that a more organised tax system, supported by better information and more effective monitoring, can help government capture revenue that might otherwise remain outside the formal tax net.
However, the significance of the growth extends beyond the headline figures. A stronger revenue base can improve the government's capacity to meet its financial obligations, support public investment and reduce the pressure to finance expenditure through additional borrowing, provided that the revenue is managed transparently and directed towards productive purposes.
For a country with substantial infrastructure deficits and a large population requiring essential public services, the ability to generate more domestic revenue represents an important step towards fiscal resilience.
Digitalisation Makes Tax Administration More Efficient
One of the most important elements of the NRS reform is the increasing use of digital technology to modernise tax administration, improve the accuracy of information available to the authorities and reduce dependence on manual procedures.
Traditionally, tax administration in a large and diverse economy such as Nigeria's has faced challenges associated with fragmented records, incomplete information, complicated filing procedures and the difficulty of monitoring transactions across multiple sectors. Digital systems offer an opportunity to address these weaknesses by making the collection, verification and processing of tax information more efficient.
The NRS has been advancing this approach through initiatives that include Rev360, electronic invoicing for large taxpayers and improvements in digital taxpayer services. The World Bank's engagement with the service in August 2026 also covered taxpayer registration, tax audits, transfer pricing, electronic invoicing and information technology-enabled administration.
Electronic invoicing is particularly significant because it can improve the visibility of commercial transactions, strengthen the verification of tax declarations and reduce opportunities for discrepancies between business records and reported income. When implemented effectively, the system can also improve the quality of information used by businesses to manage their financial obligations.
For compliant businesses, a predictable digital process can reduce the time and administrative effort required to meet tax obligations. For the revenue authority, better access to reliable information can support more targeted audits, allowing officials to concentrate their attention on areas where discrepancies or potential non-compliance are identified.
The long-term benefit is a tax administration system that relies increasingly on verifiable information, consistent procedures and efficient service delivery rather than excessive paperwork and avoidable physical interactions.
A Simpler Tax System for Businesses and Citizens
The reform also provides an opportunity to address one of the longstanding concerns of Nigeria's business community: the complexity created by fragmented tax laws and inconsistent administrative practices.
In June 2025, President Bola Tinubu signed four major tax reform laws, including the Nigeria Tax Act, the Nigeria Tax Administration Act, the Nigeria Revenue Service (Establishment) Act and the Joint Revenue Board (Establishment) Act. The new framework established a common direction for tax administration, with the relevant provisions of the Nigeria Tax Act taking effect on January 1, 2026.
The objective is to make the tax system more coherent, improve coordination among revenue authorities and establish clearer rules for taxpayers and businesses.
For entrepreneurs operating in Nigeria's competitive commercial environment, clarity matters. Businesses need to understand their obligations, anticipate compliance costs and make financial decisions without unnecessary uncertainty about the procedures governing their tax affairs.
A more harmonised framework can help reduce administrative duplication and improve consistency, although the practical benefits depend on how effectively federal and state authorities coordinate their activities and communicate the rules to taxpayers.
The reform also offers an opportunity to strengthen taxpayer education. In September 2026, the NRS reiterated its commitment to simplifying tax processes, deploying useful digital solutions and engaging directly with medium and emerging taxpayers at a town hall meeting in Kano.
Such engagement is important because effective tax administration is not achieved through enforcement alone. Businesses are more likely to comply when they understand what the law requires, can access reliable guidance and have convenient channels for resolving questions.
Expanding The Tax Base Beyond Oil
Another positive development is the increasing contribution of non-oil sources to Nigeria's revenue profile, reflecting the importance of diversifying public finances in an economy that has historically been vulnerable to fluctuations in crude oil prices.
The Economic Snapshot Report cited by The Punch indicated that non-oil revenue accounted for 76 per cent of total collections in the first half of 2026, while the country's tax-to-GDP ratio increased from 10.3 per cent to 13 per cent.
These indicators point towards a broader revenue base and an opportunity to reduce the country's vulnerability to changes in international oil prices and production levels.
A more diversified tax system can draw revenue from a wider range of economic activities, including manufacturing, services, telecommunications, finance and other formal commercial operations. It can also encourage a more systematic approach to bringing economically active businesses into the tax net.
Nevertheless, expanding the tax base should not mean imposing disproportionate burdens on businesses already struggling with high operating costs. The objective should be to improve compliance, address evasion, eliminate avoidable leakages and distribute tax responsibilities fairly.
The distinction is important because sustainable revenue growth depends on a productive economy. When businesses expand, employment increases and commercial transactions grow, the potential pool of taxable economic activity also becomes larger.
A well-administered tax system should therefore complement policies that encourage investment, enterprise development and formalisation, rather than undermine the economic activities on which future revenue depends.
A New Institutional Framework for Revenue Collection
The transformation of FIRS into the Nigeria Revenue Service is another significant feature of the reform.
The Nigeria Revenue Service (Establishment) Act, 2025 provides the legal framework for the institution's responsibility for assessing, collecting and accounting for revenue accruable to the Federal Government. The broader reform programme also seeks to improve cooperation between revenue authorities through the Joint Revenue Board framework.
The change creates an opportunity to strengthen institutional coordination and consolidate revenue administration, including the integration of non-tax revenue streams previously collected through other government agencies, as reported in the Presidency's economic review.
Better coordination can help reduce fragmentation, improve the availability of revenue information and make it easier to identify gaps in collection. It can also support more consistent reporting, which is essential for effective fiscal planning and public accountability.
The reform's success will ultimately depend on whether the institutional changes translate into measurable improvements in service delivery, stronger safeguards against revenue leakages and a more transparent relationship between government and taxpayers.
Investing In People, Technology and Institutional Capacity
The physical transformation of the revenue service has also provided a visible symbol of the institutional changes taking place.
In April 2026, President Tinubu inaugurated the 16-storey NRS headquarters in Abuja, a facility designed to accommodate approximately 3,000 employees and equipped with a data processing centre, training facilities and other staff amenities. The building had remained unfinished for more than two decades before its completion.
Beyond its physical appearance, a modern headquarters can provide an environment for improved coordination, professional development and the deployment of technology across the institution.
The greater significance, however, lies in the capacity of the organisation's workforce to adapt to increasingly digital forms of administration, analyse complex financial information and provide competent assistance to taxpayers.
Investment in staff training and technology is particularly important as commercial transactions become more sophisticated and tax authorities worldwide increasingly rely on digital records and data analysis to identify taxable activities.
For the NRS, sustained institutional development will be essential to ensuring that the improvements recorded in revenue mobilisation can be maintained without compromising fairness, efficiency or public confidence.
Turning Higher Revenue into Public Value
Ultimately, the most meaningful test of the NRS reform will be the extent to which stronger revenue mobilisation translates into tangible improvements in the lives of Nigerians.
Higher collections create greater fiscal capacity, but the benefits become more visible when public resources support reliable infrastructure, better schools and hospitals, improved security, effective public transportation and other essential services.
The reform also needs to strengthen the social contract between taxpayers and the government. Citizens are more likely to regard taxation as a legitimate civic responsibility when they can see that public funds are managed responsibly and that government institutions deliver services that justify the financial obligations imposed on them.
Equally, a modern revenue service must make compliance easier for honest taxpayers while applying the law fairly to those who deliberately evade their obligations. Transparency, accessible taxpayer support and consistent enforcement will be crucial to sustaining public confidence.
The NRS reform therefore represents more than an effort to raise additional revenue. It offers an opportunity to build a more capable public institution, improve the quality of Nigeria's tax administration and establish a stronger domestic financing base for economic development.
The revenue figures recorded since 2023 provide encouraging evidence of progress, while digitalisation, legal harmonisation and institutional restructuring offer mechanisms through which the gains could be sustained.
The next phase should focus on deepening these improvements, ensuring that smaller businesses are not overwhelmed by compliance demands, protecting taxpayers' rights and demonstrating the connection between public contributions and public benefits.
If these objectives are pursued consistently, the positive legacy of the reform could extend well beyond the revenue authority itself, helping Nigeria build a more resilient economy in which public finance depends increasingly on effective institutions, a broader productive base and a fairer, more transparent tax system.